A shorter version of an article first published at iyersellmer.com, where the full piece, chart, index table and sources are available.
In August the DAX touched 26,580, the highest level in its history. It has risen about 89% since the end of 2022. Over roughly the same period German real GDP fell about 1.2%, industrial output slipped back to around its 2005 level, and unemployment reached the 3 million mark.
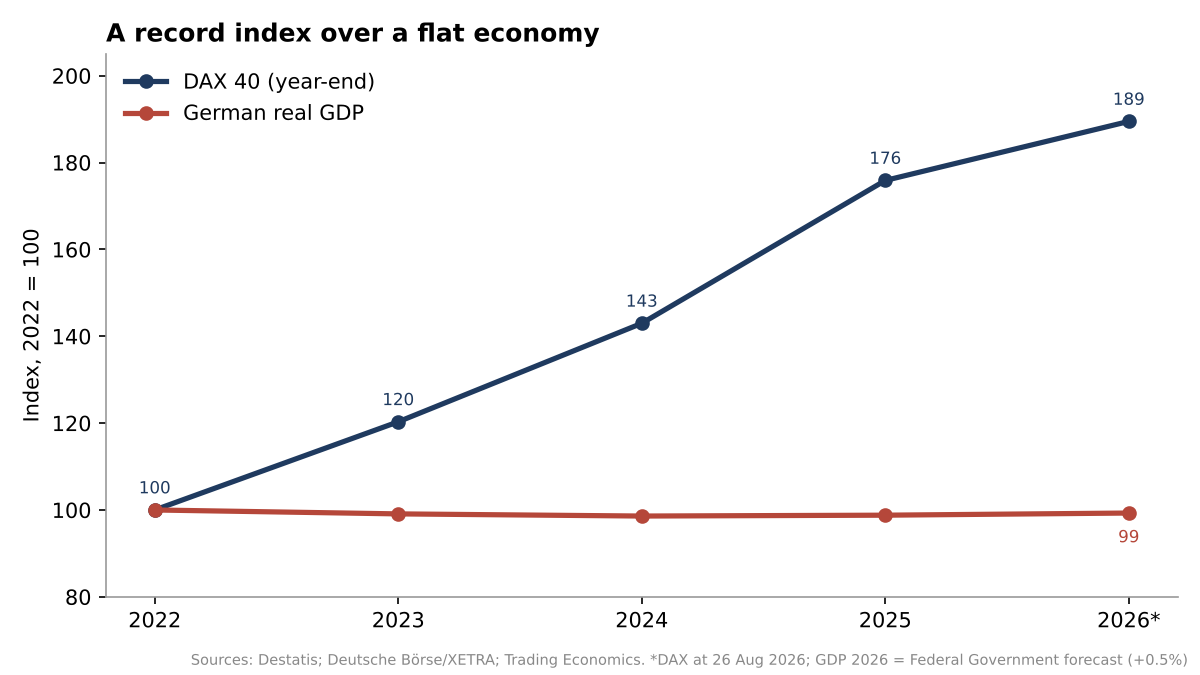
Neither number is wrong. They are measuring different countries. I count six reasons why.
The companies are German by address, not by market. Only about 18% of DAX companies’ revenue is earned in Germany, according to a Deutsche Bank analysis cited by the index operator STOXX. Siemens, SAP, Airbus, Allianz and Munich Re live off global demand. The DAX actually correlates more closely with global GDP (0.41) than with German GDP (0.33).
Profits can rise when German activity falls. GDP counts what is made inside Germany; a share price values what a company earns anywhere. When a group shuts a German plant and moves the line to Hungary or Mexico, German output drops and the company’s margins can improve. Manufacturing output fell 1.3% in 2025, the third fall in a row, and the market read much of that restructuring as good news.
The index no longer looks like the economy. No German carmaker is among the DAX’s fifteen largest members, and none weighs more than about 2.4%. Car exports to China fell from nearly €30bn in 2022 to under €14bn in 2025, which shows up starkly in the trade data and barely at all in the index. The Mittelstand, where most Germans work and most of the strain sits, is mostly in the MDAX, the SDAX or not listed at all.
Germany keeps score differently. The headline DAX is a performance index that counts reinvested dividends. The S&P 500, CAC 40 and FTSE 100 are quoted as price indices. The DAX price index stands near 9,500 against about 26,000 for the performance version. That’s worth roughly three percentage points a year that other countries’ headline numbers don’t count.
Markets price 2029; GDP reports 2025. In March 2025 the Bundestag approved a €500bn infrastructure fund over twelve years and exempted defence spending above 1% of GDP from the debt brake. Markets repriced a decade of orders at once; Rheinmetall, Renk and Hensoldt more than doubled in 2025. The Bundesbank expects the real spending to pick up only from the second quarter of 2026.
The buyers aren’t German either. EY found that foreign investors held 52.6% of DAX share capital in 2024, with Americans alone at 25.4%. The marginal price setter is a global fund manager comparing Frankfurt with New York, and at about 13 times forward earnings at the end of 2024, Germany looked cheap.
Where the neat story doesn’t hold
It isn’t the whole picture. The more domestic MDAX and SDAX also rose about 19% and 22% in 2025, so this was partly a broad re-rating of German shares on the fiscal package. The defence rally has partly unwound, with Rheinmetall down about 26% over the year to late August. And the euro rose about 15% against the dollar in 2025, which hurt foreign earnings rather than flattering them. The DAX rose anyway.
What it means
The DAX is unrepresentative of Germany by design. It ranks the forty largest and most liquid listed companies, which means big, global, largely foreign-owned firms, and it leaves out the domestic economy where the trouble is. “The DAX is one of Europe’s best performers” is true. It just isn’t a statement about German growth, jobs or household incomes.
For a read on the domestic economy, watch the MDAX and SDAX, the ifo index, the PMI, insolvencies and construction orders. And compare the DAX with other markets on a like-for-like basis, or Germany gets three free points a year.
Whether the economy catches up with what the market is pricing depends on how quickly that €500bn turns into real orders. The Bundesbank’s December forecast had growth at 0.6% this year and 1.3% next. The market is betting on more.
The full version, with the chart, a table of the DAX’s largest members and a complete source list, is at iyersellmer.com. This is a personal analytical piece, not investment advice.